
A year ago, we argued that SPACs had entered a fourth, more disciplined era: experienced sponsors, longer search periods, promotes tied to performance, and targets with real revenue.[1] Twelve months on, that thesis has held. This article discusses where the bottleneck would move.
In 2021 the scarce resource was a credible target. In 2026, it is committed cash at closing. There are plenty of SPACs and plenty of companies that want to use them. What there is not, outside a narrow band of sectors, is a PIPE.
How the money moves
A SPAC is a company with no business — a management team, a pile of cash and a deadline. The team sells units, usually a share bundled with a fraction of a warrant, to the public at $10 each. Nearly all of the proceeds go into a trust invested in short-term U.S. government securities. The team then has 12 to 24 months under its charter to find a private company to buy, extendable by sponsor deposits or a shareholder vote, and 36 months at the outside under the exchange listing rules.
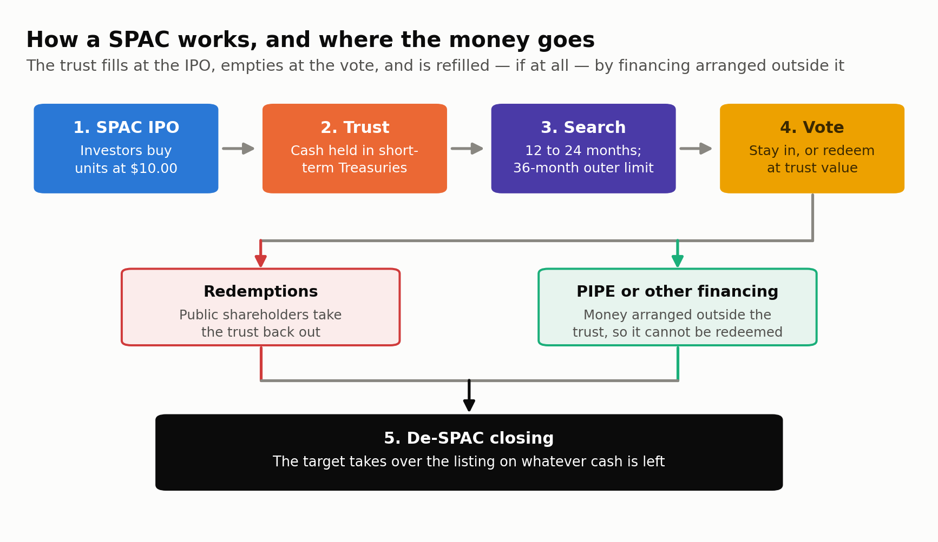
Read it left to right: the trust fills at the IPO, empties at the vote, and is refilled — if at all — by money arranged outside it.
The catch is in the fine print. When a deal is announced, every SPAC shareholder gets a choice: stay in and own a piece of the new company, or hand back the shares and take a pro rata share of the trust (referred to as a redemption). In 2021 most investors stayed. Today most leave. In every quarter of 2025, the median de-SPAC lost more than nine public shares in ten.[3] Many of today’s SPAC investors appear to buy at the IPO already planning to cash out at the vote. To them the trust is a savings account with a free lottery ticket attached.
Here is what that does to a typical trust. The average SPAC raised about $211 million in 2025, and the average across 2026 pricings has slipped to roughly $176 million.
The trust is full, the exit door is open, and the backstop that used to catch the deal is thin.
So how do deals actually get done?
By treating the PIPE as one tool among many rather than the closing condition. Six patterns recur in this year’s closed and pending deals.
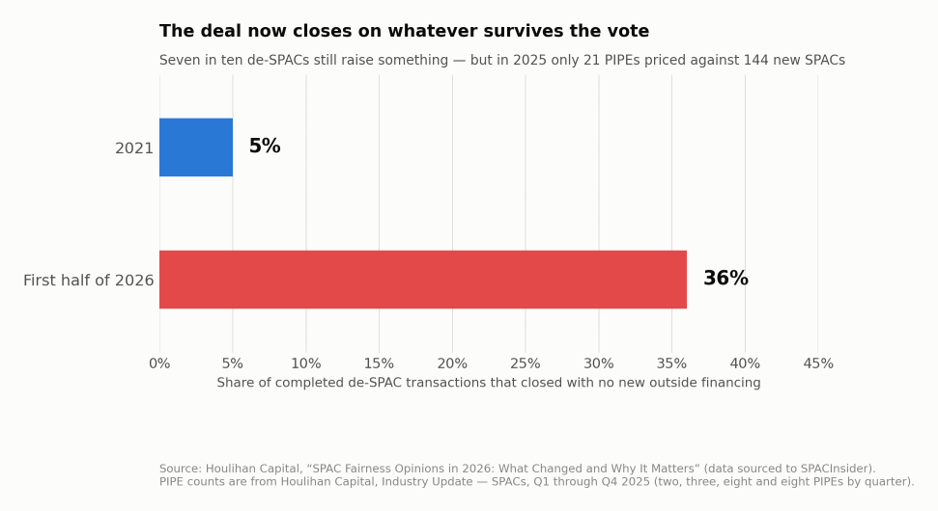
Close on less cash. About 36 percent of de-SPACs in the first half of 2026 closed with no new outside financing at all, against roughly 5 percent in 2021.[19] Minimum cash conditions are sized to what survives redemptions, and target holders cover the shortfall by taking more stock instead of cash. The de-SPAC becomes a listing, not a capital raise. The raise comes later.
Non-redemption agreements. Sponsors pay holders not to redeem, in founder shares rather than cash. In one 2025 arrangement, DT Cloud Star Acquisition Corp.’s sponsor agreed to transfer 200,000 founder shares at closing to a holder who agreed not to redeem 600,000 shares at an extension vote.[20] That is one free share for every three held, paid out of the promote. It works, and it dilutes everyone else.
Prepaid forward purchase agreements. Live Oak V and Teamshares, and GigCapital7 and Hadron, each paired non-redemption agreements with prepaid forwards, and both closed in 2026.[21] A counterparty buys shares from holders who would have redeemed and settles up later. In both deals the prepayment was funded out of the trust, so the structure preserved the share count against a minimum cash condition rather than delivering new money to the company — and the stock still carries an overhang, sharpened by reset mechanics that reprice the counterparty’s economics downward as the shares fall.
Backstops and structured PIPEs. Sponsors, anchor investors and strategic partners commit to buy shares only if redemptions push cash below a floor. And where a PIPE exists at all, it is rarely plain common stock: convertible notes and preferred give investors downside protection, but conversions weigh on the stock right after closing.[22]
Raise after the listing. Equity lines have become a common post-close facility, letting the company sell stock in small pieces to a committed buyer as it needs cash. Newsmax signed a $1.2 billion standby facility in 2025; most de-SPAC lines are a fraction of that.[23] In May 2026 the SEC proposed an overhaul of the registered offering framework that would drop the one-year reporting history now required for Form S-3, which would let a company emerging from a de-SPAC use a shelf immediately and make “list now, raise later” materially cheaper.[24] The proposal has not been adopted.
In-kind and strategic money. The Bitcoin Standard Treasury deal took roughly $600 million of its PIPE in bitcoin rather than cash — 5,021 bitcoin, alongside up to $1.5 billion of fiat-denominated financing — yet the shareholder vote was postponed three times while terms were renegotiated, and the parties ultimately terminated.[25] Strategic money solves the check-size problem. It does not solve the confidence problem.
When a real PIPE does show up, it now does a different job. A PIPE signed before the deal is announced validates the valuation; one raised afterward is just extra cash. The sectors where anchors still write checks — infrastructure, defense, data centers and digital assets — share one trait: revenue that exists today. That is last year’s discipline thesis, restated as a financing rule.
What this means
For sponsors: line up the financing before the letter of intent, not after, and size the target to the trust. The exchanges’ 80 percent test is a floor, not a target, and dilution drives the math.[26]
For targets: a SPAC nearing its deadline is a motivated seller, and founder shares are negotiable. But a listing without capital is a liability, not an asset. Model the post-closing float, the forward and convertible overhang, and the cost of the equity line before you sign.
For both: every tool above moves value from one pocket to another, and each of them, if material, must be described in the de-SPAC disclosure documents under the SEC’s 2024 SPAC rules — principally Items 1603 through 1605 of Regulation S-K — and is separately reportable on Form 8-K.[27] The plaintiffs’ bar reads proxy statements. The litigation risk we flagged last year now lives in the financing annex.[28]
The bottom line
SPAC 4.0 fixed the target problem. SPAC 4.1 has to fix the capital problem. The vehicles are there and the companies are there. The sponsors who thrive will be the ones who stop asking “who will PIPE this?” and start engineering the close from the redemption line up.
[1]Louis Lehot & Alexandre Turqueto, SPAC 4.0: From Spectacular Failures to a Disciplined Renaissance, Foley & Lardner LLP (Sept. 30, 2025), https://www.foley.com/insights/publications/2025/09/spac-4-0-from-spectacular-failures-to-a-disciplined-renaissance/.
[2]Nasdaq IM-5101-2; NYSE Listed Company Manual § 102.06, https://listingcenter.nasdaq.com/rulebook/nasdaq/rules.
[3]Jay R. Ritter, Special Purpose Acquisition Company (SPAC) IPOs, Table 12 (updated July 10, 2026), https://site.warrington.ufl.edu/ritter/files/IPOs-SPACs.pdf.
[4]Boardroom Alpha, SPAC IPO Tracker, https://www.boardroomalpha.com/spac/ipos.
[5]Renaissance Capital, US IPO Market: 2021 Annual Review (Jan. 2022), https://www.renaissancecapital.com/review/2021USReview_Public.pdf; Ritter, supra note 3, Table 15b; Special Purpose Acquisition Companies, Shell Companies, and Projections, Release Nos. 33-11265; 34-99418; IC-35096 (Jan. 24, 2024), 89 Fed. Reg. 14158 (Feb. 26, 2024), Table 1 n.25, https://www.sec.gov/files/rules/final/2024/33-11265.pdf.
[6]Nasdaq, A Record Year for IPOs in 2021, https://www.nasdaq.com/articles/a-record-year-for-ipos-in-2021.
[7]Houlihan Capital, SPAC Fairness Opinions in 2026: What Changed and Why It Matters, https://www.houlihancapital.com/spac-fairness-opinions-in-2026-what-changed-and-why-it-matters/.
[8]Michael Klausner & Michael Ohlrogge, Was the SPAC Crash Predictable?, 40 Yale J. on Reg. Bull. 101 (2023), https://www.yalejreg.com/wp-content/uploads/Michael-Klausner-Michael-Ohlrogge-Was-the-SPAC-Crash-Predictable-40-Yale.-J.-on-Regul.-Bulletin-101-2023.pdf.
[9]Michael Eisenband, Not Even a Raging Bull Market Can Rescue SPACs, FTI Consulting (July 9, 2024), https://www.fticonsulting.com/insights/articles/not-even-raging-bull-market-can-rescue-spacs.
[10]SPAC Conference 2026 Market Survey, DealFlow Events (June 18, 2026), https://www.accessnewswire.com/newsroom/en/publishing-and-media/spac-conference-2026-market-survey-pipe-funding-remains-crucial-to-successful-1179045.
[11]Renaissance Capital, DAT SPAC: The crypto sell-off has punished digital asset treasury companies (Mar. 10, 2026), https://www.renaissancecapital.com/IPO-Center/News/117578/DAT-SPAC-The-crypto-sell-off-has-punished-digital-asset-treasury-companies-.
[12]Cantor Equity Partners I, Inc., Current Report (Form 8-K) (Aug. 20, 2026), https://www.sec.gov/Archives/edgar/data/2027708/000121390026092163/ea0302895-8k_cantor1.htm.
[13]Chibuike Oguh, Danilo Masoni & Medha Singh, Selloff wipes out nearly $1 trillion from software and services stocks as investors debate AI’s existential threat, Reuters (Feb. 4, 2026), https://finance.yahoo.com/news/global-software-stocks-hit-anthropic-120659089.html; Louis Lehot, Private Equity’s Hard Year Has Real Openings, Foley & Lardner LLP (Sept. 21, 2026), https://www.foley.com/insights/publications/2026/09/private-equitys-285-billion-shock-year-still-has-real-openings/.
[14]SPAC Conference 2026 Market Survey, supra note 10.
[15] SPAC Insider, https://www.spacinsider.com/data/stats
[16]Boardroom Alpha, SPAC IPO Tracker, supra note 4.
[17]Houlihan Capital, Industry Update — Special Purpose Acquisition Companies, Q1 2026, https://www.houlihancapital.com/wp-content/uploads/2026/08/Q1-2026-SPAC-Report-v2.pdf.
[18]Boardroom Alpha, DeSPAC Tracker, https://www.boardroomalpha.com/spac/despacs.
[19]Houlihan Capital, SPAC Fairness Opinions in 2026, supra note 7.
[20]DT Cloud Star Acquisition Corp., Current Report (Form 8-K) (Oct. 22, 2025), https://www.sec.gov/Archives/edgar/data/2017950/000149315225018928/form8-k.htm.
[21]Live Oak Acquisition Corp. V, Current Report (Form 8-K) (June 1, 2026), https://www.sec.gov/Archives/edgar/data/2048951/000121390026063576/ea0292781-8k425_liveoak5.htm; GigCapital7 Corp., Current Report (Form 8-K) (May 7, 2026), https://www.sec.gov/Archives/edgar/data/2023730/000119312526211817/d152235d8k.htm.
[22]Cantor Equity Partners I, Inc., Current Report (Form 8-K), Ex. 99.1 (July 22, 2025), https://www.sec.gov/Archives/edgar/data/2027708/000121390025064927/ea024932301ex99-1_cantor1.htm.
[23]Newsmax Inc., Current Report (Form 8-K) (Apr. 7, 2025), https://www.sec.gov/Archives/edgar/data/2026478/000121390025029186/ea0237300-8k_newsmax.htm.
[24]Registered Offering Reform, Release Nos. 33-11418; 34-105513; IC-36160 (May 19, 2026), 91 Fed. Reg. 31022 (May 26, 2026), https://www.federalregister.gov/documents/2026/05/26/2026-10373/registered-offering-reform.
[25]Cantor Equity Partners I, Inc., Form 8-K, Ex. 99.1, supra note 21.
[26]Nasdaq IM-5101-2; NYSE Listed Company Manual § 102.06, supra note 2.
[27]17 C.F.R. §§ 229.1603–229.1605, https://www.ecfr.gov/current/title-17/chapter-II/part-229/subpart-229.1600; Form 8-K, Item 1.01.
[28]Delman v. GigAcquisitions3, LLC, 288 A.3d 692 (Del. Ch. 2023), https://courts.delaware.gov/Opinions/Download.aspx?id=342240; Solak v. Mountain Crest Capital LLC, C.A. No. 2023-0469-SG (Del. Ch. Oct. 18, 2024), https://law.justia.com/cases/delaware/court-of-chancery/2024/ca-no-2023-0469-sg.html.
Louis Lehot is a partner at Foley & Lardner LLP in Silicon Valley, San Francisco, and Los Angeles, advising founders, venture capital investors, and boards on M&A, public offerings, venture financing, and corporate governance. His path runs through two decades inside Big Law, a Silicon Valley boutique he founded, and a deliberate return to Big Law at Foley in 2021, where Chambers USA has ranked him in Venture Capital (California) every year since, and in Startups & Emerging Companies (USA - Nationwide) in 2025 and 2026. He has written more than 50 articles on deal markets and publishes The Weekly Silicon Valley Docket at louislehotattorney.substack.com.
Legal
Subscribe To Our Newsletter
Stay updated by subscribing to our newsletter
Attorney advertising – prior results do not guarantee a similar outcome.
Opinions expressed here are my own and not those of my law firm.
Please read and acknowledge the following before using this AI Assistant:
• This AI Assistant provides information for general informational purposes only and does not constitute legal, tax, financial, medical, or other professional advice.
• Responses are generated by artificial intelligence and may be incomplete, inaccurate, or outdated. Important information should be independently verified.
• Use of this AI Assistant does not create an attorney-client relationship with Louis Lehot or any affiliated law firm.
• Do not submit confidential, sensitive, or privileged information through this chat.
• Decisions should not be based solely on AI-generated responses. Please consult a qualified professional for advice specific to your situation.
• This website and AI Assistant may be considered attorney advertising in some jurisdictions.
• Past performance is not a guarantee of future outcomes. AI-generated responses are not a guarantee of future outcomes or accuracy.
• By selecting “I Agree”, you acknowledge that you have read, understood, and accepted this disclaimer.